INDUSTRIAL
 MARKET ENVIRONMENT
FY15 has been a tale of two markets. Industries and exports less dependent on utilities, like
warehousing, remain more resilient. Conversely, those industries with exposure to commodities
and Rand weakness were most sluggish. This trend was clear in our diversified industrial portfolio.
The slowdown in developments resulted in the gradual take-up of the overhang of new industrial
property stock, so normality is returning to the market. In addition, there is less exuberance in the
market, making expectations more realistic now.
User commitment remains intact, albeit with shorter lease terms and less capital commitment.
South Africa traditionally has a resilient culture and its people have a tendency to find new ways to
thrive in changing conditions.
There is an increased appreciation of industrial property as a subsector, with its perceived resilience,
historical lower rentals and higher capitalisation rates. Our talented industrial team includes skilled
people who together have weathered negative cycles before, so we are also enjoying the benefits
of a stable, experienced group of specialised industrial property professionals.
Our sector faces challenges from the rising interest rate environment, water and electricity
cost increases, load shedding, labour unrest, declining commodity prices and the slump in retail
sales. Motor vehicle sales, considered a proxy for the industrial property sector, were negative.
Manufacturing confidence is the lowest in 10 years. We also face infrastructure failure and an
increasing number of business failures and business rescues. The failure of Ellerines is one of the
most significant examples, leaving Growthpoint’s industrial portfolio with a 46 000m2 vacancy.
The industrial sector’s performance in FY15 was largely sentiment driven. There was less
commitment to expansion, lower capital investment and our users had a distinct focus on
cost-cutting. Responding to this, we have applied significant focus on ways of reducing energy
consumption and recovering utilities costs. Research around sustainability initiatives has also
accelerated, driven by market conditions. We’ve also explored other revenue streams.
PERFORMANCE
Three years ago we identified a difficult cycle approaching as telegraphed in our report of FY14.
It is firmly here.
The performance of our diversified portfolio remains positive, although different subsectors are
affected differently by the prevailing cycle.
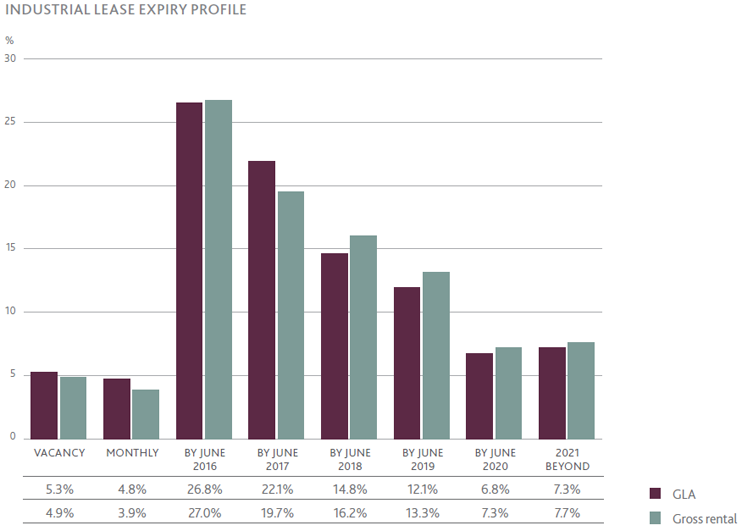
We have kept rental escalations positive, in excess of 8.0%. We’ve also kept our arrears at
satisfactory levels and placed strong emphasis on utilities management and recoveries. However,
vacancies are increasing, renewal growth is mid-single digit and lease terms are shorter.
The impact of the Ellerines business failure was significant for us. Several other large vacancies also
occurred during the year, mostly because of the underlying economic forces. For a short time, our
vacancy factor reached the highest level it had been in five years. This has already improved. We’ve
achieved significant lettings that will bring vacancies down to market-related levels.
Rent renewals remained under pressure. For us the emphasis was strongly on keeping clients,
especially as we believe the sector will remain under pressure for the foreseeable future.
| Bringing world-class facilities to market
at attractive yields |
 ENVIRONMENTAL
COMMITMENT
After the success of our environmentally
innovative Grundfos development, which
achieved the first Green Star SA rating for an
integrated industrial and office development,
we have actively explored including sustainable
elements in all our developments and
redevelopments. Greenfield Industrial Park is
one such development.
There is still no green rating tool for the sector,
so we are continually learning and applying the
skills from our counterparts in the office and
retail sectors. However, there is now a GBCSA
Green Star SA tool under development. GBCSA
has accepted our Greenfields Industrial Park
development, near Cape Town International
Airport, as a pilot project for its Green Star SA
Industrial building rating tool. This confirms
our cutting-edge position in providing green
industrial buildings.
One of our latest initiatives is to integrate solar
PV on rooftops. This has huge potential benefits
for our clients.
Where possible, we use clients as the suppliers
of the materials, skills and services we need. This
vertical integration within our portfolio also
provides business-to-business opportunities
for our clients. It has really taken off and is proving to be yet another important advantage
for our clients.
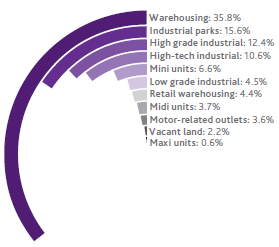
| INDUSTRIAL VALUE BY TYPE |
 |
PROSPECTS
After experiencing tough trading for FY15,
largely due to the Ellerines demise and
several other large vacancies, we believe our
diversified portfolio should offer some
resilience in FY16.
The negative drivers of the sector are all factors
outside our control. We remain focused on that
which we do well and can control. Our focus is
on our core portfolio, our clients, lease retention
and value extraction from the portfolio.
We have a solid development pipeline to stand
us in good stead and have some superb land
opportunities, specifically Samrand, Wadeville
and a site on the R300 in Cape Town. In
addition, acquisitive growth has become a
reality because of normalising capitalisation
rates and seller expectations.
Besides seeking alternative revenue streams,
we are fortunate our portfolio values per
square metre and in-force gross rentals are still
relatively low. This creates an opportunity for
upward adjustment. We also have a solid team
with vast experience.
All this places us in a position to weather the
storm of the coming year.
| Offering a full range of industrial facilities to our client base |
| Value adding joint ventures |
| Strategic land acquisitions |
Key performance areas
| |
FY15 |
|
FY14 |
|
Increase/
(decrease) |
|
| Gross property revenue (R’million) |
1 149 |
|
1 074 |
|
75 |
|
| Property expenses (R’million) |
(257) |
|
(235) |
|
22 |
|
| Net property income (R’million) |
892 |
|
8398 |
|
53 |
|
| Property expense ratio (%) |
22.4 |
|
21.9 |
|
0.5 |
|
| Vacancies (%) |
5.3 |
|
3.0 |
|
2.3 |
|
| Arrears (R’million) |
9,3 |
|
4,9 |
|
4,4 |
|
| Bad debt provision (R’million) |
3,8 |
|
1,7 |
|
2,1 |
|
| Average gross rental (R per m2/month) |
43 |
|
42 |
|
1 |
|
| Forward yield (%) |
10.1 |
|
10.1 |
|
– |
|
| Average in-force escalation (%) |
8.4 |
|
8.3 |
|
0.1 |
|
| Weighted average lease period (years) |
2.8 |
|
2.9 |
|
(0.1) |
|
| Asset value (R’billion) |
10,4 |
|
9,3 |
|
1,1 |
|
| Number of properties |
229 |
|
230 |
|
(1) |
|
| GLA (m2) |
2 225 075 |
|
2 194 459 |
|
30 616 |
|
| Value (excluding bulk) per m2 (R) |
4 589 |
|
4 127 |
|
462 |
|
| Capital expenditure (R’million) |
530 |
|
234 |
|
296 |
|
Top 10 industrial tenants
| |
Tenant |
GLA*
m2 |
|
% of
total industrial
GLA |
|
| 1 |
The Bidvest Group Limited |
57 036 |
|
2.7 |
|
| 2 |
Adcock Ingram Holdings Limited |
27 280 |
|
1.3 |
|
| 3 |
Scania SA Proprietary Limited |
23 341 |
|
1.1 |
|
| 4 |
Kulingile Metals Proprietary Limited (Robor) |
49 000 |
|
2.3 |
|
| 5 |
Distell Limited |
45 658 |
|
2.2 |
|
| 6 |
The Laser Transport Group Proprietary Limited |
36 013 |
|
1.7 |
|
| 7 |
Allied Electronics Corporation Limited |
27 872 |
|
1.3 |
|
| 8 |
Pioneer Foods Proprietary Limited |
20 734 |
|
1.0 |
|
| 9 |
Barloworld Limited |
18 516 |
|
0.9 |
|
| 10 |
DCD Dorbyl Proprietary Limited |
72 252 |
|
3.4 |
|
| Total of Top 10 |
377 702 |
|
17.9 |
|
| * Ranked in terms of gross monthly rental |
Top 10 industrial properties by value
| |
Property name |
|
Location |
Value
Rm |
|
% of total
industrial portfolio |
|
GLA*
m2 |
|
% of
industrial
GLA |
|
| 1 |
Growthpoint Industrial Estate |
|
Germiston |
388 |
|
3.7 |
|
61 245 |
|
2.8 |
|
| 2 |
Hilltop Industrial Park |
|
Germiston |
325 |
|
3.1 |
|
74 089 |
|
3.3 |
|
| 3 |
Montague Business Park (25%) |
|
Cape Town |
322 |
|
3.1 |
|
19 470 |
|
0.9 |
|
| 4 |
Adcock Ingram |
|
Johannesburg |
205 |
|
2.0 |
|
21 536 |
|
1.0 |
|
| 5 |
Rivonia Crossing 2 |
|
Sandton |
186 |
|
1.8 |
|
19 778 |
|
0.9 |
|
| 6 |
N1 Business Park (20%) |
|
Midrand |
183 |
|
1.8 |
|
18 937 |
|
0.9 |
|
| 7 |
Omni Park |
|
Johannesburg |
178 |
|
1.7 |
|
41 331 |
|
1.9 |
|
| 8 |
Central Park |
|
Cape Town |
163 |
|
1.6 |
|
49 135 |
|
2.2 |
|
| 9 |
Kulungile Building |
|
Kempton Park |
153 |
|
1.5 |
|
49 000 |
|
2.2 |
|
| 10 |
Meadowbrook Estate |
|
Germiston |
142 |
|
1.4 |
|
9 684 |
|
0.4 |
|
| Total of Top 10 |
|
|
2 245 |
|
21.7 |
|
364 205 |
|
16.5 |
|
| INDUSTRIAL PROPERTIES TOP 10 BY VALUE |
| 2 225 075m2 total GLA |
| R1,1 billion total revenue |
| We believe our diversified
portfolio should offer some
resilience in FY16 |
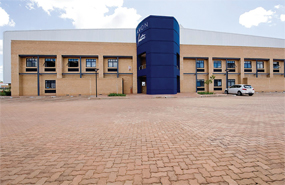
| GROWTHPOINT INDUSTRIAL ESTATE |
GERMISTON |
The 61 245m2 A-grade industrial park is situated on a 259 455m2 site in the
Route 24 node in Meadowdale. Valued at R388 million, it provides around-the-
clock cutting-edge security in an environmentally respectful and
energy efficient setting for 32 businesses. It is 96% let and major tenants
include Barloworld Logistics, Avon Justine, Fast & Furious and Ricoh SA.
Growthpoint Industrial Estate has 40 000m2 of available bulk for tenant
driven developments. |
 |
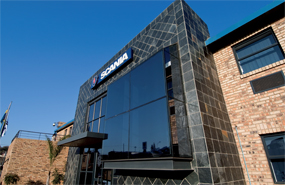
| HILLTOP INDUSTRIAL PARK |
GERMISTON |
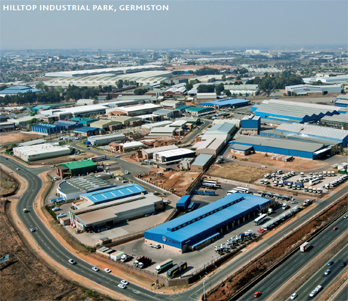
With superb highway frontage and access, Hilltop Industrial Estate
encompasses some of the most functional industrial premises in South
Africa. This B-grade industrial park is valued at R325 million and is currently
undergoing a major upgrade. It comprises 19 businesses in 74 089m2 of
lettable area on a 263 446m2 site area. It is 95% let and major tenants
include Scania, Cartoon Candy, Capital Africa Steel and MAN Diesel and
Turbo SA. |
 |
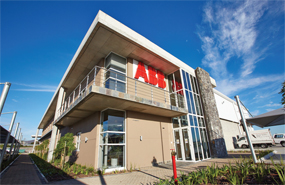
| MONTAGUE BUSINESS PARK (25%) |
CAPE TOWN |
Growthpoint’s 25% joint ownership of this newly developed industrial
park is valued at R322 million and represents a current GLA of 19 470m².
This A-grade industrial park, in the sought after Montague node, is home
to 18 businesses, which include leading brands such as Takealot.com,
Supergroup, ABB SA and The Radiant Group. There is high demand for
further development of the park’s available bulk. |
 |
| ADCOCK INGRAM |
JOHANNESBURG |
This 21 536m2 A-grade property is a key facility for leading South African
pharmaceutical company Adcock Ingram Healthcare. It has a site area of
47 011m2, is fully let to Adcock Ingram and valued at R205 million. |
 |
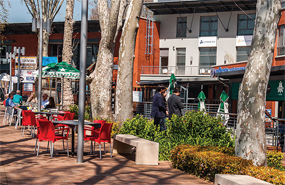
| RIVONIA CROSSING 2 |
SANDTON |
This well-located showroom and value centre spans 19 778m2 of A-grade
lettable area on a 37 933m2 site. This multi-tenant centre is fully let and
houses 17 tenants and is valued at R186 million. Its major tenants include
Honda Rivonia, The Barnyard Theatre and Safari and Outdoor Warehouse. |
 |
| N1 BUSINESS PARK (20%) |
MIDRAND |
Growthpoint’s 20% stake in the well located park between Midrand and
Pretoria is valued at
R183 million and represents a GLA of 18 937m². With
superb visibility to the busy N1 motorway, this A-grade industrial park
is home to 14 businesses including Shoprite, Mazda SA, Elliot Mobility,
Zodiac, Tevo and MTN. The landscaped and high security N1 Business Park
is almost completely developed. |
 |
|
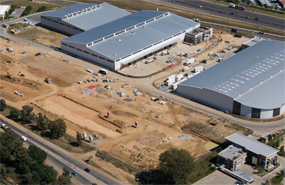
With its superb position in the high-demand Aeroton industrial node, this
industrial park is 85% let. It provides 41 331m2 of B-grade industrial space
on an 85 014m2 site area. The property’s appeal is underpinned by excellent
highway access, to both the north and south of Johannesburg. It is valued at
R178 million and major tenants include BCE Food Services and Brandcorp. |
 |
|
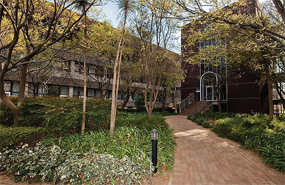
This landscaped industrial park provides exceptional security and good
access to main arterials for
24 businesses in 49 135m2 of A-grade space on
a site area of 97 216m2. Valued at R163 million, it is fully let and is home
to major tenants Retail Logistics, Fawecia Emissions Control and Conop
Projects. |
 |
| KULUNGILE BUILDING |
KEMPTON PARK |
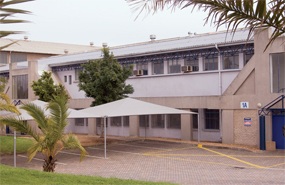
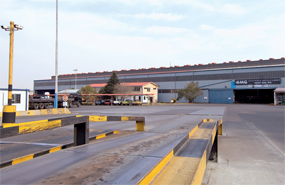
This single tenanted, large industrial facility is situated in the prominent
industrial node of Isando. With a lettable area of 49 000m² under roof,
gantries and cranes in all bays and large yard areas this industrial facility is
valued at R153 million. |
 |
| MEADOWBROOK ESTATE |
GERMISTON |
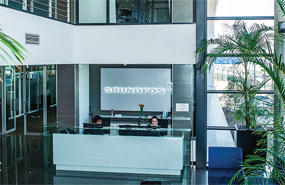
Home to Grundfos, this 9 684m² facility is situated on the very prominent
intersection of the N12 and R24 interchange. This high–tech facility, with
superb visibility to two major motorways, is valued at R142 million. This
5-Star, Green Accredited, integrated office and industrial facility represents
the very best of South African property innovation and is the first property
to have been awarded this accolade. |
 |